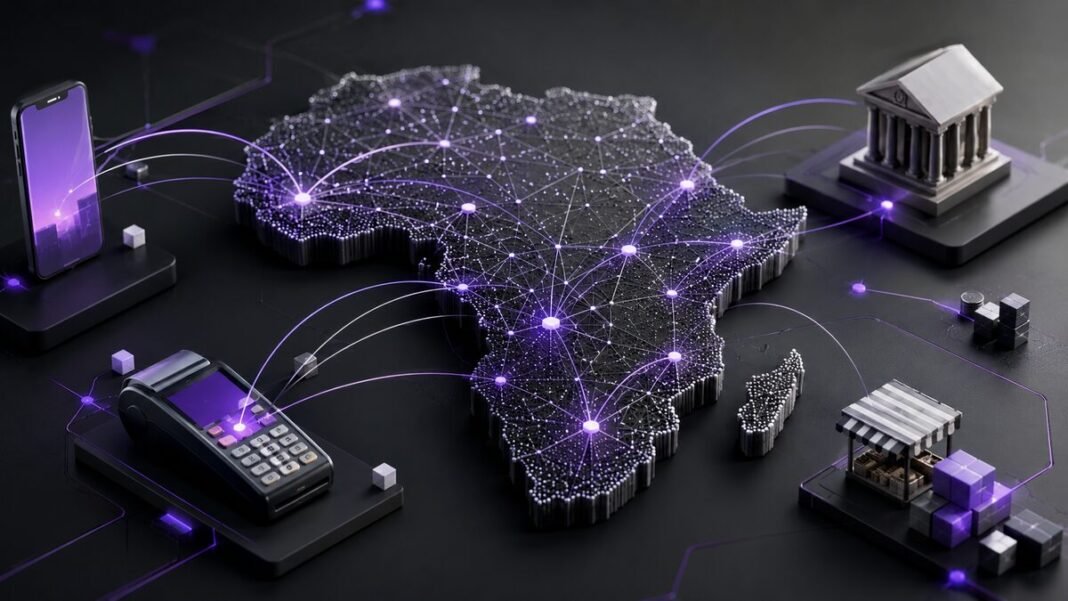
FinTech in Africa now covers far more than mobile transfers. Technology is reshaping how people and businesses pay, save, borrow, insure, invest and move money across borders. The market is maturing, so sustainable growth increasingly depends on trust, regulation, distribution and healthy economics as much as product innovation.
Africa is not one financial market. Kenya, Nigeria, South Africa, Egypt, Ghana and other markets differ in banking penetration, currencies, payment rails and regulation. The useful approach is to understand shared forces without pretending that one model fits every country.
FinTech in Africa: what matters in 2026
The strongest common direction is that finance is becoming more digital, more mobile and increasingly embedded inside commerce and business workflows. Mobile money, instant payments, digital banking, responsible credit and better identity infrastructure are converging.
The World Bank Global Findex 2025 tracks account ownership and digital payments, while the GSMA mobile-money report shows the continuing expansion of mobile financial services.
1. Mobile money is becoming a platform
Mobile money increasingly connects transfers with merchant payments, bills, savings and credit. The opportunity is moving from another wallet toward infrastructure and services around existing distribution. See Mobile Money in Africa.
2. Instant payments are becoming infrastructure
Fast payment systems can reduce friction between banks, wallets and merchants. The World Bank’s 2026 instant-payments paper highlights interoperability and inclusion as core priorities.
3. Digital banking is shifting competition
Customers compare onboarding, fees, reliability, support and access to useful services. A polished app is not a moat. Read Digital Banking in Africa for the banking side of this shift.
4. Cross-border finance remains difficult
African businesses, freelancers and families still face currency conversion, compliance, liquidity and settlement friction. Solving cross-border payments is valuable, but it is operationally harder than building a domestic consumer app.
5. Responsible credit can widen access
Digital data can help assess customers with limited conventional credit histories, but poor affordability checks can create harm. The World Bank has examined inclusive credit FinTechs in Africa.
6. Security is a competitive advantage
More digital finance creates more opportunities for impersonation, account takeover and social engineering. Strong authentication, monitoring and dispute resolution can differentiate providers. See Cybersecurity in Africa.
7. Inclusion is moving beyond account counts
A registered account creates limited value if it is too costly, confusing or unsafe to use. Meaningful Financial Inclusion in Africa depends on repeated and useful activity.
What this means in practice
For founders, the attractive opportunity is often behind the visible transaction: merchant tooling, reconciliation, identity, fraud prevention, interoperable rails, SME finance and cross-border infrastructure. For businesses buying FinTech services, reliability and integration can matter more than headline fees.
- Identify the expensive financial job before choosing technology.
- Compare total cost, including integration, settlement and support.
- Test reliability with real transactions before scaling.
- Review regulatory status, security controls and complaint handling.
- Measure retention and unit economics rather than vanity user counts.
Risks and trade-offs to understand
Regulatory change, fraud, weak connectivity, device affordability, currency volatility and expensive customer acquisition can slow growth. Funding conditions also matter when investors demand clearer paths to profitability. The broader lessons in African Startups apply strongly to FinTech.
Consumers and companies should treat security as part of product quality, not a separate technical issue. TechBrief’s Online Account Security guide explains practical controls that reduce account-takeover risk.
A simple decision framework
- Define the customer problem and how often it occurs.
- Identify the current alternative, including cash or manual work.
- Check whether regulation or licensing constrains the model.
- Measure distribution cost and the reason customers will stay.
- Test security, reliability and dispute resolution.
- Scale only when economics and customer outcomes remain healthy.
Frequently asked questions
What is FinTech in Africa?
It is the use of technology to deliver or improve financial services across African markets, including payments, banking, lending, insurance, investment and infrastructure.
Why is African FinTech growing?
Mobile adoption, demand for easier payments, gaps in conventional access, digital commerce and improving infrastructure all support growth.
Is African FinTech only mobile money?
No. Mobile money is important, but the ecosystem also includes digital banking, payments, credit, remittances, identity, fraud prevention and financial infrastructure.
What is the biggest opportunity?
There is no single winner across all markets. Durable opportunities often solve interoperability, SME finance, cross-border payments, fraud or merchant problems.
Bottom line
Africa’s FinTech opportunity remains large, but the market is becoming more disciplined. The businesses most likely to endure will solve expensive problems, earn trust, navigate regulation and build distribution competitors cannot copy easily.
Next step: read Digital Payments in Africa to understand the rails underneath the wider FinTech shift.
Business models that can create durable FinTech value
A FinTech business needs a clear answer to who pays and why the service remains valuable after promotional incentives disappear. Transaction fees can work when payment volume is large and margins remain healthy. Subscription software can work for merchants when it saves measurable staff time or improves control. Lending can generate attractive revenue but introduces credit risk, funding costs and collections responsibilities. Infrastructure providers may earn through APIs or platform fees, but enterprise sales cycles can be longer.
The strongest model is not automatically the one with the highest headline margin. It is the model where distribution cost, compliance cost, fraud losses and customer support remain manageable as volume grows. Founders should therefore model contribution margin per active customer or transaction, not just total processed value. A product that moves billions while losing money on each customer is not necessarily a strong business.
For a deeper view of capital discipline, see Startup Funding in Africa. FinTech founders should use funding to accelerate a model that is becoming stronger, not to hide weak retention or unsustainable incentives.